Table Of Content ☰
- 1. Introduction
- 2. 15-Year vs 25-Year Home Loan: At a Glance
- 3. How Does Loan Tenure Affect EMI?
- 4. Benefits of a 15 Year Home Loan
- 5. Benefits of a 25 Year Home Loan
- 6. 15-Year vs 25-Year Home Loan: What Should You Consider?
- 7. When a 15-Year Home Loan May Fit Your Situation
- 8. When a 25-Year Home Loan May Fit Your Situation
- 9. Conclusion
- 10. Why HouseGyan?
- 11. FAQs
Introduction
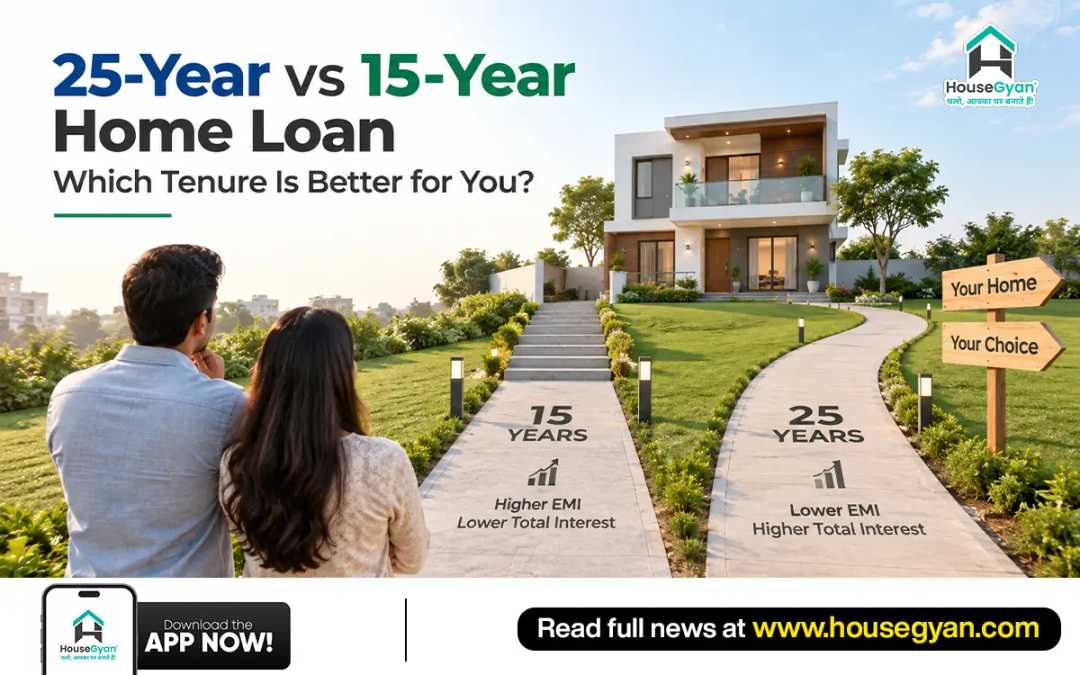
The decision on whether to take a 15-year home loan or 25-year loan has an impact on the EMI, overall interest, and time to repay the loan. A shorter tenure implies greater EMIs and lesser interest, whereas a longer tenure implies lower EMIs and greater overall interest. Select according to your income and budget.
15-Year vs 25-Year Home Loan: At a Glance
A 15 year home will offer high EMIs and tend to offer lower aggregate interest and quicker repayment. A 25 year home loan has fewer monthly EMIs but more total interest. Evaluate both alternatives on your income, costs, repayment ability, and financial objectives.
How Does Loan Tenure Affect EMI?
The length of the loan has a direct impact on your EMI; the short term reduces the monthly payments at the cost of a lesser total interest, and an extended tenure lowers the EMI and results in a higher aggregate interest. Before making a decision, compare the EMI to your monthly income, expenses, savings, and other financial commitments.
Example of EMI Difference
For example, consider a ₹50 lakh home loan at an assumed 8.5% annual interest rate:
Benefits of a 15 Year Home Loan
Fast loan recovery.
Decrease in total interest charge.
Immediately creates home ownership.
Assist in lowering long-term debt.
This fits borrowers who are able to bear increased EMIs.
May provide greater financial flexibility after the loan ends.
Benefits of a 25 Year Home Loan
Lower monthly EMI.
Less difficult to control in relation to other expenses.
Borrowers with low monthly surplus.
Provides a longer repayment period.
May help maintain emergency savings.
Is able to make home ownership more affordable at the beginning of the income.
Read More: 10 Things to Compare Before Choosing a Home Loan Bank.
15-Year vs 25-Year Home Loan: What Should You Consider?
Take into account these aspects when choosing your tenure:
Monthly income: This will show how much EMI you can easily afford.
Total interest: Compare the total interest paid on both.
Financial goals: consider retirement planning and other loans, investments, and savings.
Job stability: The better the EMI, the more income ought to be stable.
Emergency fund: Do not spend all the monthly excess on EMI payments.
Future expenses: Consider education, family needs, or other major expenses.
Prepayment options: Find out whether you can make the extra payments in future.
Interest rate: Your EMI and repayment can be affected by fluctuations in the rate.
When a 15-Year Home Loan May Fit Your Situation
A 15-year loan can be suitable to borrowers who have a stable income and have enough surplus monthly to afford a larger EMI. It may be adequate when the total interest and an earlier debt-free status are significant financial objectives. Compare the EMI with your normal expenses before taking the short tenure.
When a 25-Year Home Loan May Fit Your Situation
A 25-year loan can suit those who want to pay lower monthly EMI and who require an increased budget; it may be a good option when you have other financial obligations or you wish to save more. But look at the greater aggregate interest in a longer payback period.
Conclusion
A mortgage of 15 years will not add up to the same cumulative interest but with an increased EMI. A 25 year mortgage has a reduced EMI but can be more expensive in terms of total interest expense. Use your income, expenses, savings, financial aspirations, and repayment capacity to compare with and save and repayment capacity before selecting the tenure that fits best.
Why HouseGyan?
HouseGyan is a straightforward and useful source of knowledge on buying a home, borrowing, interior, and property choices. Our guides make you see key factors in a better way in order to make your home and finances make better choices.
FAQs
1. Is a 15-year home loan cheaper than a 25-year loan?
Usually, yes. The shorter the tenure, the less the overall interest, but the higher the monthly EMI.
2. Is a 25-year home loan better for lower EMI?
Generally, yes, an individual will lower the monthly EMI by spreading the repayment over a longer period.
3. Can I repay a 25-year home loan early?
Yes, if you and your lender agree. Check applicable charges and prepayments.
4. How much does tenure affect home loan interest?
The longer the tenure, the higher the total interest is likely to be due to the fact that the loan is outstanding.
5. Should I choose EMI affordability or a shorter tenure?
You should select an EMI that you can comfortably pay without having to examine your savings and other financial obligations.
6. Can I change my home loan tenure later?
Certain lenders might tolerate the transfer of tenures but on their terms and conditions. Ask your lender about the available options.